A revocable living trust is the cornerstone of a well-structured estate plan because it combines flexibility with clarity. Grantors who choose this type of trust arrangement are free to update it as needed and direct how their assets are transferred to the beneficiaries after death, without having to pass through probate.
At Pierro, Connor & Strauss, we help New Yorkers in the Capital Region create trusts that align with their legacy and wishes for their loved ones. With our guidance, our clients make thoughtful, informed decisions about the various types of trusts available under New York law. On this page, we will discuss one of the most practical and flexible options we set up for our clients every day, the revocable living trust.
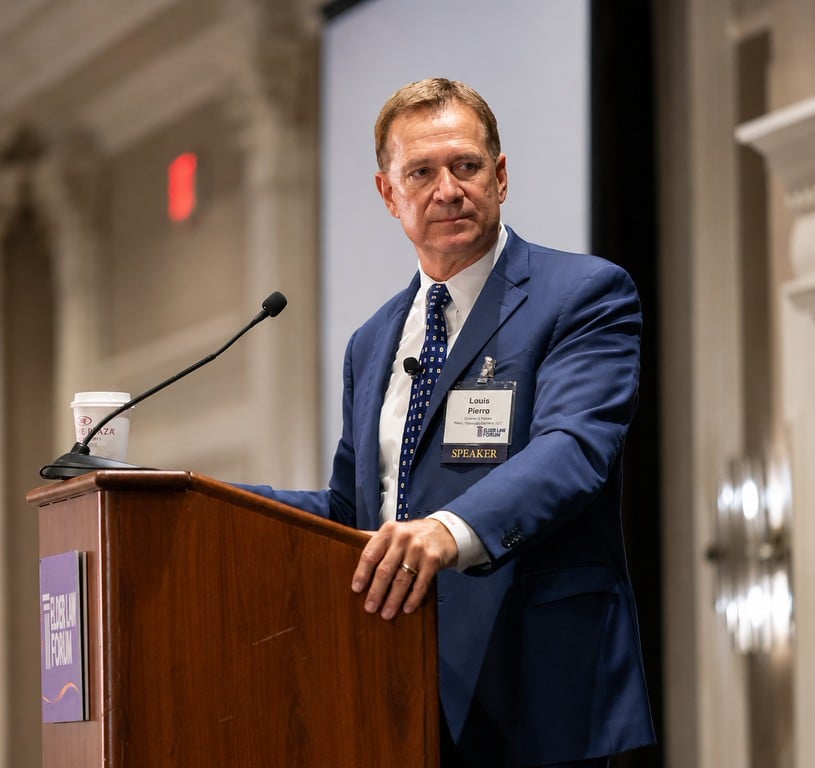
“A Revocable Living Trust can do something a will cannot: provide a framework for managing trust assets during your lifetime, including if you become incapacitated, and then transition those assets to your beneficiaries without the need for probate. Over more than 40 years, I’ve seen how that continuity can make a significant difference for families: providing greater privacy, efficiency and control at times when they need it most.”
—Louis Pierro, Founding Partner
What Is a Revocable Living Trust?
A revocable living trust is a way to hold and manage assets in the name of a trust while you’re alive, and then transfer them to the people or organizations you choose, such as family members, loved ones, or charities, after your death, according to your written instructions.
It’s “revocable” because the grantor retains control. As the creator of the trust, you can change the terms, move assets in or out, or revoke the trust entirely at any time during your lifetime.
For many families, the practical value is this: a properly funded trust can make the transition after death smoother and more private than relying on a will alone, and it can also provide a clear plan for managing trust assets if you’re ever temporarily or permanently unable to handle financial matters due to illness or injury.
Albany Trusts Team
Louis W. Pierro
AARON E. CONNOR
Frank E. Hemming III