A Beneficiary Defective Inheritor’s Trust (BDIT) is among the more sophisticated tools available for individuals seeking to transfer appreciating assets, preserve meaningful control and address estate, income-tax and asset-protection objectives.
At Pierro, Connor & Strauss, LLC, our attorneys design, structure and implement BDITs for individuals, business owners and families with complex wealth-transfer needs. Creating a BDIT requires far more than preparing a trust agreement. It requires sophisticated legal and tax planning to structure the trust, select and transfer the right assets, allocate trustee powers and integrate the strategy with the client’s broader estate plan.
Our attorneys bring together decades of experience in estate planning, tax planning, asset protection, business succession and trust administration to develop BDIT strategies tailored to each client’s circumstances.
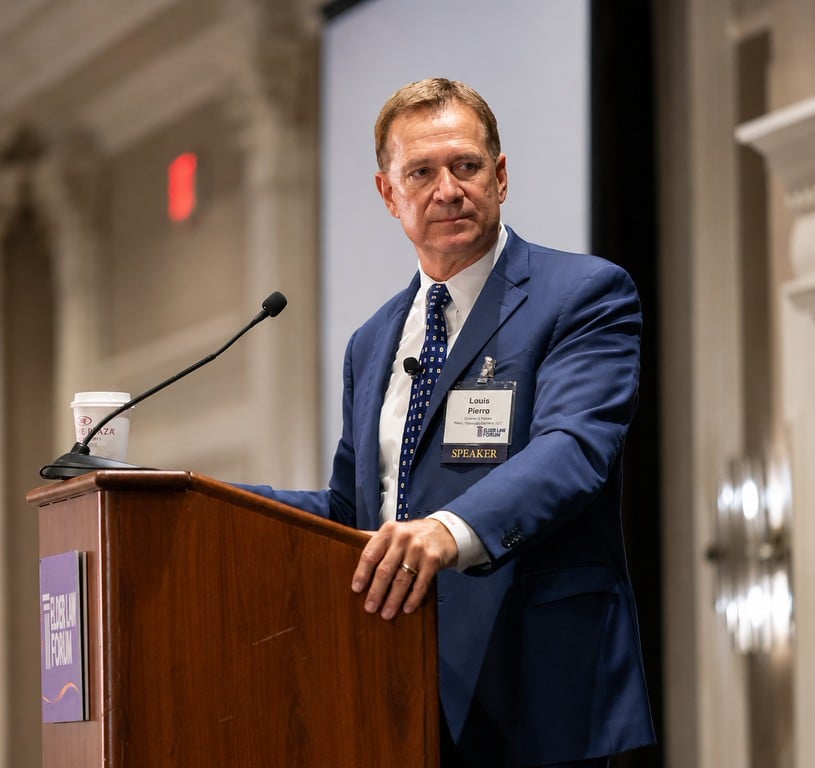
“BDITs are a powerful tool for high-net-worth clients who want to move appreciating assets outside their taxable estates without giving up meaningful access or control. I have designed and implemented BDIT strategies for clients with substantial business and investment interests, and I have seen firsthand how these trusts can reduce estate-tax exposure, provide asset protection and facilitate long-term wealth transfer.”
—Louis Pierro, Founding Partner
What Is a Beneficiary Defective Inheritor’s Trust?
A BDIT is an irrevocable trust established and initially funded by someone other than the primary beneficiary. The trust is designed so that the beneficiary is treated as the owner of the trust for federal income tax purposes while the trust assets may remain outside the beneficiary’s taxable estate for estate tax purposes.
The “defective” aspect refers to the trust’s income-tax treatment. Through carefully drafted provisions, the beneficiary may be treated as the owner of the trust for federal income tax purposes, even though the trust is structured to keep its assets outside the beneficiary’s taxable estate.
This combination can create a powerful planning opportunity: the beneficiary may retain meaningful investment and management responsibilities while future appreciation on assets held in the trust may occur outside the beneficiary’s taxable estate. Achieving that result requires careful coordination of the beneficiary’s powers, the trustee’s responsibilities and the trust’s distribution provisions.